How to score and prioritize acquisition targets on your M&A longlist
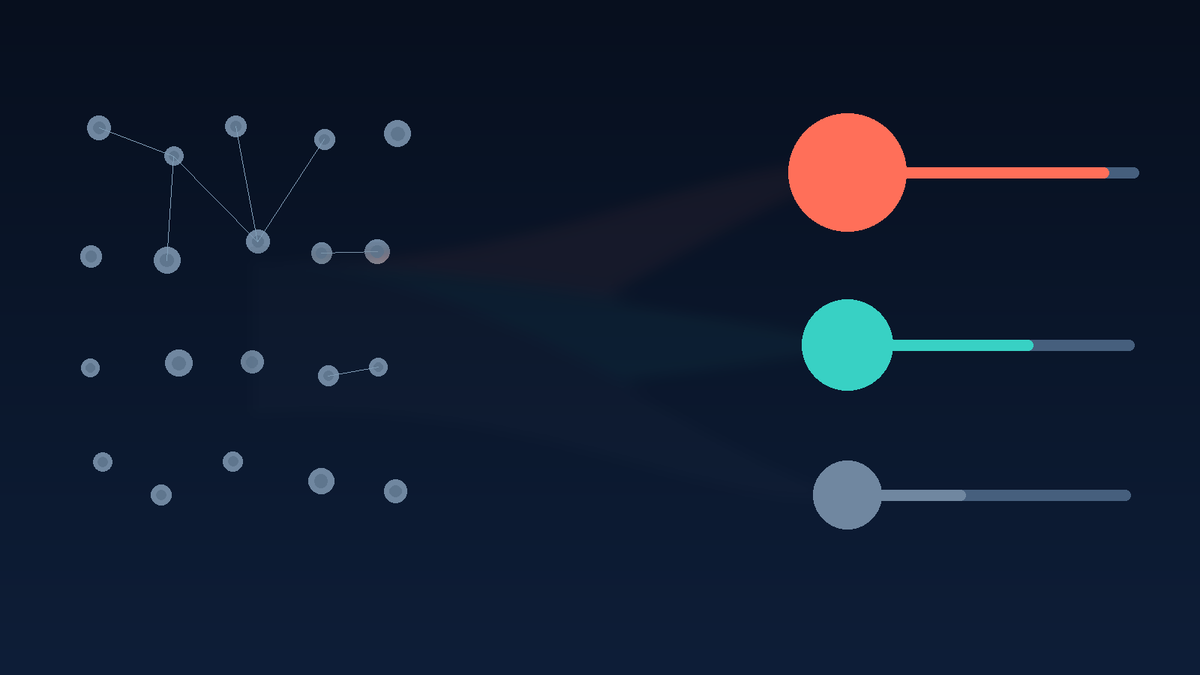
A longlist with two hundred names on it is not a plan, it is a to-do list nobody can start. Once sourcing has done its job and produced a long, broad list of potential acquisition targets, the real bottleneck shifts. The question is no longer “how do we find targets,” it is “which ones do we call first, and why.”
Scoring and prioritizing a longlist is the step between sourcing and outreach. Done well, it turns an undifferentiated list into a small number of tiers that tell the deal team exactly where to spend time first, and it gives everyone from associates to the investment committee a shared, defensible reason for that order.
In this article you’ll learn:
- Why an unscored longlist quietly wastes the most expensive hours on a deal team
- The criteria that belong in most acquisition target scoring models, and how they differ by deal thesis
- How to weight criteria so the score reflects your actual strategy, not a generic checklist
- How to turn a score into tiers your team can act on, instead of a spreadsheet nobody reopens
- Where structured company data and AI remove the slowest part of scoring at scale
- The most common mistakes that make a scoring model useless within a quarter
Why an unscored longlist slows down the whole deal process
A longlist exists to be acted on, but most teams treat every name on it the same way until something forces a decision, usually a deadline or a bandwidth problem. Without a score, prioritization defaults to whoever is loudest in the room, whichever company the lead banker mentioned last, or simply the order the list happened to be sorted in.
That default is expensive. Outreach, management calls, and early diligence are the most time-intensive parts of the sourcing funnel, and they are usually spent in roughly the order targets were added to the list rather than in the order they are likely to convert into a deal. A scoring model does not replace judgment, it makes the judgment explicit and consistent across the team, so the targets most likely to fit the thesis and actually transact get the first calls.
The real cost of treating every target the same
Deal teams rarely measure how much time a longlist actually costs them, because the cost is spread across weeks of calls, meetings, and partial diligence rather than showing up as a single line item. A 150-target longlist that gets worked top to bottom without scoring means the team can easily spend a third of its outreach capacity on companies that were never a strong fit on strategy, size, or ownership situation.
The opportunity cost compounds on live deals. While a team is chasing a target that was always a weak match, a better-fit target further down the unscored list is sitting untouched, and a competing acquirer may get there first.
What an acquisition target scoring model actually does
A target scoring model converts the signals a deal team already gathers, financials, market position, ownership structure, strategic overlap, into a single comparable number per target. It does not replace the underlying analysis. It forces that analysis to happen consistently for every name on the list, rather than only for the targets someone already likes.
The output is not meant to be a precise ranking down to a decimal. It is meant to separate a long list into a small number of groups, usually three or four, so the team knows where to spend the next round of hours.
Six criteria most M&A target scoring models should include
The exact list varies by deal thesis, but most workable models for corporate M&A, advisory, and private equity screening draw from the same six categories:
Common scoring criteria for an M&A target longlist
| Criterion | What it measures | Typical data source |
|---|---|---|
| Strategic fit | How closely the target's product, customer base, or geography extends the buyer's stated thesis | Deal thesis brief, product and customer mapping |
| Financial health | Revenue trend, margin profile, leverage, and cash conversion | Filed accounts, or estimated financials for private companies without public filings |
| Market position | Share within its segment, competitive intensity, and pricing power | Market sizing and peer benchmarking |
| Valuation expectation | Likely multiple versus comparable transactions, set against the buyer's return hurdle | Precedent transactions and public comparables |
| Deal readiness | Signals such as owner age, succession situation, prior sale attempts, or time since the last funding round | Ownership and management data, public filings |
| Synergy and integration fit | Realistic cost or revenue synergies against the operational complexity of integrating the target | Internal synergy model, organizational and systems review |
Two criteria are worth calling out because teams routinely get them wrong. Strategic fit is often scored on gut feel rather than a written thesis, which makes it impossible to compare across reviewers. And deal readiness is frequently skipped entirely, even though a perfect strategic match with an owner who has no intention of selling is not a near-term opportunity, regardless of how high it scores on everything else.
How to weight the criteria for your specific thesis
A single generic weighting does not work across deal types, because the criteria that predict a good outcome shift with the buyer's objective.
- Platform or buy-and-build acquirers typically weight strategic fit and deal readiness highest, since the point is to find willing sellers who extend a thesis, not necessarily the largest or most profitable company available.
- Private equity financial buyers tend to weight financial health and valuation expectation more heavily, since the return has to work on its own even before synergies are considered.
- Strategic bolt-on acquisitions inside a larger group usually weight synergy and integration fit highest, because the case for the deal often rests on cost or revenue synergies rather than the target's standalone financial profile.
The specific weights matter less than writing them down and applying them consistently. A simple 1 to 5 score per criterion, multiplied by a weight that sums to 100%, is enough to produce a defensible ranking without turning the exercise into a modeling project.
From score to shortlist: tiers your team will actually use
A raw numeric score is hard to act on directly. What works in practice is converting the score into three or four tiers with a clear next action attached to each one:
Example tiering after scoring
| Tier | Profile | Next action |
|---|---|---|
| Tier A | Top-scoring targets, strong fit across most criteria | Direct outreach or warm introduction within the next sourcing cycle |
| Tier B | Good fit on some criteria, gaps on others, worth monitoring | Light-touch research, revisit at the next longlist review |
| Tier C | Weak fit or low deal readiness today | Park, but keep in the universe for future cycles |
A review cadence matters as much as the tiers themselves. Deal readiness signals change: an owner approaches retirement age, a competitor gets acquired, a company takes on debt. A longlist scored once and never revisited drifts out of date within a quarter, which is one of the most common reasons scoring efforts get abandoned.
Where structured data and AI shorten the scoring cycle
Most of the time a scoring exercise takes is spent pulling the underlying data together, not deciding on the weights. Estimating revenue and margins for a private target with no public filings, checking ownership structure, or benchmarking against the right peer group can each take an analyst hours per company, and a 150-name longlist multiplies that fast. This is the part of the process where structured company data and AI genuinely remove hours rather than just add another dashboard. StrategyBridgeAI pulls financial, ownership, and market data from a database covering roughly 50 million public and private companies across more than 100 countries, so a deal team can populate most scoring criteria for an entire longlist in one pass instead of researching each target individually, with teams typically cutting the research time behind a longlist or screening exercise by about 80% compared to a fully manual process. With our dynamic, web-enriched columns, you can easily add custom data points based on web research to filter down to the results you really need to get a shortlist. Talk to us about scoring your next longlist.
Common mistakes that make a scoring model useless after one quarter
- Too many criteria. Past six or seven, scoring becomes a data entry exercise instead of a decision tool, and consistency between reviewers drops.
- Weights set once and never revisited. A thesis shift, a new mandate, or a market change should trigger a review of what the model rewards, not just which targets are on the list.
- Scoring on stale data. A score built on a 12-month-old estimate of revenue or an outdated ownership structure produces a ranking that looks precise and is quietly wrong.
- No clear owner for keeping the list current. If updating scores is nobody's explicit job, the list decays until the next full sourcing cycle starts from scratch.
- Conflating interest with fit. A target that is easy to reach, because someone on the team already knows the owner, is not the same as a target that scores well on strategic and financial criteria.
Frequently asked questions
What is a target scoring model in M&A?+
A target scoring model is a structured way to rank acquisition targets on a longlist by assigning a comparable numeric score to each one, based on criteria such as strategic fit, financial health, market position, valuation expectation, deal readiness, and synergy potential. It replaces ad hoc prioritization with a consistent, defensible order for outreach.
How many criteria should an M&A scoring model use?+
Most workable models use five to seven criteria. Fewer than that risks missing an important dimension, such as deal readiness, while more than seven to eight tends to turn scoring into a data entry exercise and makes it harder for different reviewers to apply the model consistently.
How do you move from a longlist to a shortlist?+
Score every target on the longlist against the same weighted criteria, then group the results into three or four tiers rather than relying on a precise rank order. The top tier becomes the shortlist for immediate outreach, while lower tiers are parked for monitoring or a future sourcing cycle.
Should strategic buyers and private equity firms use the same scoring criteria?+
The underlying categories, strategic fit, financial health, market position, valuation, deal readiness, and synergy, apply to both, but the weighting differs. Platform and buy-and-build acquirers typically weight strategic fit and deal readiness highest, while financial buyers tend to weight financial health and valuation expectation more heavily.
How often should a target score be updated?+
Deal readiness and market position signals change on the scale of months, not years, so an active longlist is usually worth rescoring at each sourcing review cycle, commonly quarterly, or sooner if a specific target has a material change, such as a new owner, a competitor acquisition, or a funding event.
Can AI help score acquisition targets?+
AI and structured company data mainly speed up the data-gathering side of scoring, estimating financials for private companies, mapping ownership structures, and benchmarking against peers, so a deal team can populate scoring criteria for an entire longlist at once rather than researching targets one by one. The weighting and final judgment on fit still sit with the deal team.
More from this category
Explore related insights from StrategyBridgeAI.

Cross-border deal sourcing: how to find acquisition targets in a market you don't know
A practical playbook for sourcing and screening acquisition targets in a country where you have no local network, from building the universe to first contact.
How to source add-on acquisition targets for a buy-and-build strategy
Add-ons are now the default deal in European private equity. Here is how to build an add-on pipeline that covers the whole target universe, not just the part already for sale.
How to source add-on acquisitions for a buy-and-build strategy
Add-on sourcing fails when the target universe is too small, not when the process is too slow. A practical method for building a buy-and-build pipeline that holds.